 Agency News
Barbara Bako, Abuja
The National Insurance Commission (NAICOM) has called on insurance company directors to strengthen corporate governance and risk management practices, warning that the successful completion of the industry’s recapitalisation exercise must translate into stronger institutions and improved protection for policyholders.
The Commissioner for Insurance and Chief Executive of NAICOM, Olusegun Ayo Omosehin, said the next phase of the industry’s development would depend largely on how companies manage their capital, supervise risks and maintain financial discipline.
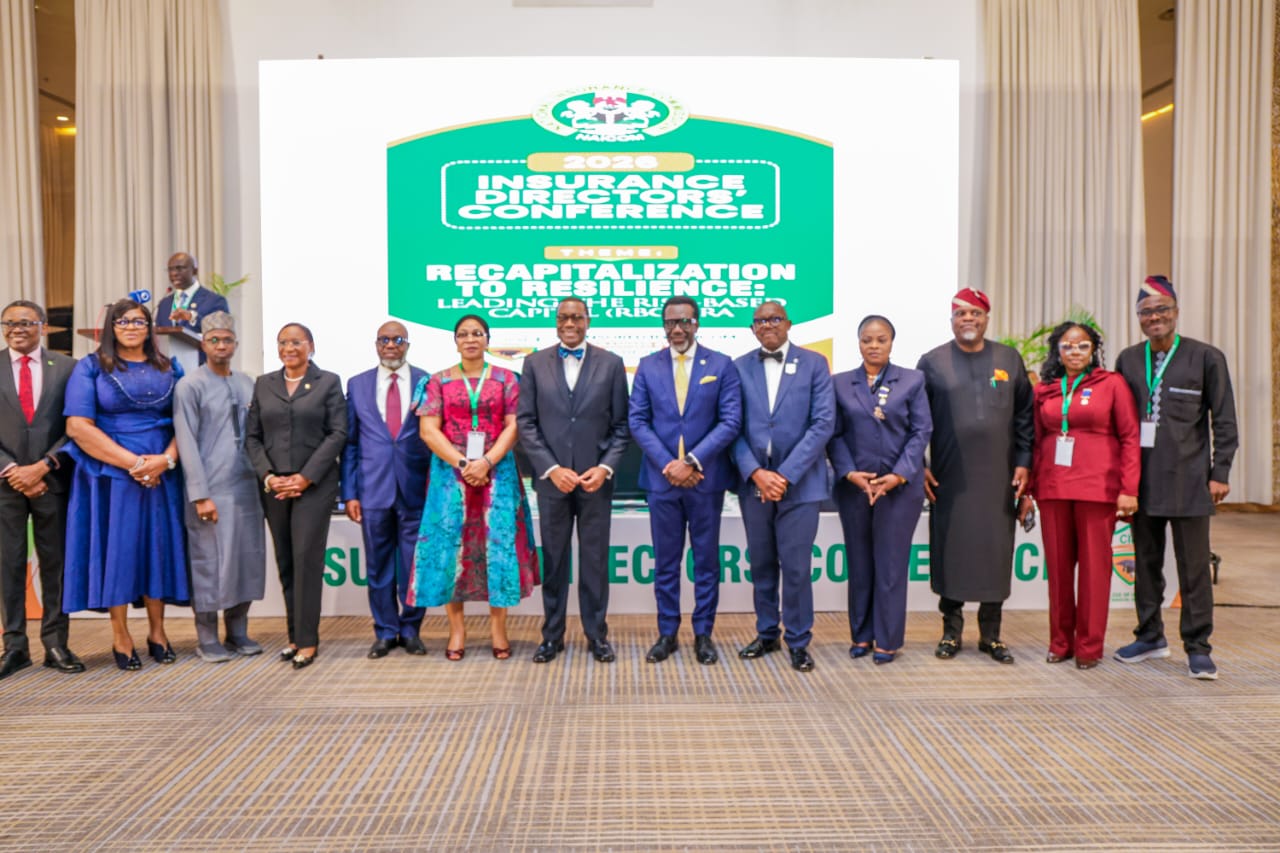
He made this known on Thursday at the 8th Annual Insurance Directors’ Conference in Lagos, themed, “Recapitalisation to Resilience: Leading the Risk-Based Capital (RBC) Era.”
Omosehin described the recapitalisation exercise as a foundation for a more resilient insurance industry, noting that the real test would be the ability of companies to deploy their enhanced capital prudently and sustain growth without exposing themselves to excessive risks.
He cautioned that a large capital base did not automatically translate into financial stability, citing poor governance, weak internal controls, inappropriate investments and inadequate board oversight as factors capable of undermining even well-capitalised institutions.
According to him, insurance boards must move beyond routine oversight and take a more active role in challenging management decisions, evaluating business strategies and ensuring that companies operate within approved risk limits.
He said directors must pay particular attention to underwriting exposures, reinsurance arrangements, investment risks, liquidity, operational vulnerabilities and technology-related threats.
The Commissioner also stressed the need for stronger accountability between boards and executive management, warning that shareholders’ expectations for higher returns must not override the industry’s obligations to policyholders, creditors and other stakeholders.
On the transition to Risk-Based Capital, Omosehin explained that the framework would require insurers to maintain capital commensurate with the risks they undertake, rather than relying solely on compliance with prescribed minimum capital thresholds.
He distinguished between the Minimum Capital Requirement (MCR), which establishes the minimum capital required to operate a licensed insurance business, and Risk-Based Capital, which assesses the capital needed to support an institution’s specific risk exposures.
He noted that an insurer could meet the minimum capital requirement but still lack sufficient capital to cover the scale and complexity of its operations.
Omosehin said NAICOM would consequently strengthen its supervisory focus on capital quality, risk management systems, corporate governance, actuarial assessments and the accuracy of financial disclosures.
He warned that completing recapitalisation would not shield insurance companies from continued regulatory scrutiny, emphasising that capital adequacy must be maintained throughout their operations.
“Capital adequacy is a continuous responsibility. Institutions must remain financially sound and compliant throughout their operations,” he said.
The Commissioner further urged insurers to strengthen internal audit, compliance and risk management functions, ensuring that identified weaknesses were promptly reported and addressed.
He also called for strict adherence to Fit and Proper requirements in appointing directors and senior management personnel, saying appointments must reflect professional competence, integrity, experience and ethical standing.
Beyond regulatory compliance, Omosehin said the recapitalisation exercise should position the insurance industry to play a more significant role in Nigeria’s economic development.
He identified infrastructure, energy, manufacturing, agriculture and construction as key sectors that require a financially strong insurance industry to support investments and manage complex risks.
According to him, stronger domestic insurance capacity would also provide opportunities to reduce dependence on foreign insurance markets, expand long-term institutional investment and deepen insurance penetration.
However, he said the industry must improve product innovation, service delivery and claims settlement to translate its stronger financial position into greater public confidence.
He maintained that policyholders ultimately measure the strength of insurance companies by their ability and willingness to honour contractual obligations when claims arise.
Omosehin urged industry directors to use the post-recapitalisation period to improve governance standards, strengthen institutional resilience and build an insurance sector capable of supporting sustainable economic growth.